

CBAM Explained: The EU’s Carbon Border Adjustment Mechanism
Read summarized version with:
 ChatGPT
 Gemini
 Perplexity
 Claude
 Grok
The Carbon Border Adjustment Mechanism (CBAM) entered into force on January 1, 2026, placing a carbon cost on certain goods imported into the EU. For companies that source carbon-intensive products from outside the EU, the CBAM creates concrete financial and operational obligations, from tracking product-level emissions to purchasing certificates and coordinating with global suppliers.
Key Takeaways
- The EU’s Carbon Border Adjustment Mechanism places a carbon cost on steel, aluminum, cement, fertilizers, electricity and hydrogen imports, ensuring imported goods face the same climate accountability as EU-produced ones.
- CBAM is now in full effect. Financial obligations apply to all imports made from January 1, 2026 onward.
- Compliance requires accurate, product-level emissions data from non-EU suppliers. The less reliable your supplier data, the higher your costs.
- CBAM is not a one-time filing. It requires ongoing supplier engagement, accurate data and cross-functional coordination.
What Is the Carbon Border Adjustment Mechanism (CBAM)?
The Carbon Border Adjustment Mechanism (CBAM) is the EU’s carbon pricing system for imports. It mirrors the costs that EU manufacturers pay under the Emissions Trading System (EU ETS), ensuring that imported goods face the same carbon accounting as domestically produced goods.
The primary goal is to prevent carbon leakage. Without a mechanism like CBAM, companies could sidestep EU climate costs by relocating production to countries with weaker environmental oversight, or EU industries could lose ground to cheaper imports produced without equivalent carbon constraints. CBAM closes that gap by applying a carbon cost at the point of entry.
CBAM currently applies to six categories of carbon-intensive goods:
- Iron and steel
- Aluminum
- Cement
- Fertilizers
- Electricity
- Hydrogen
For companies importing any of these products into the EU, CBAM is a climate accountability mechanism that extends across procurement decisions, supplier relationships and ESG reporting.
How CBAM Works
CBAM applies a carbon cost to imported goods that reflects the price EU manufacturers pay under the Emissions Trading System (EU ETS). If you import covered products into the EU, you must account for the greenhouse gas emissions produced during manufacturing. Compliance involves three core obligations:
- Calculate the embedded emissions in each imported product
- Submit an annual CBAM declaration
- Purchase CBAM certificates equal to the emissions reported
The price of a CBAM certificate mirrors the weekly average price of EU ETS allowances. If the foreign producer has already paid a carbon price, you can deduct that amount. This prevents double pricing for the same emissions.
CBAM calculates embedded emissions using three options:
- Actual emissions data from the producer
- Approved equivalent methods
- Default values provided by the European Commission
Default values are conservative estimates calculated from the emissions intensity of the worst-performing producers in a sector. They apply only when actual data or an approved method isn’t available. Because they’re deliberately set high, using real supplier data typically results in lower reported emissions and reduced CBAM costs.
The CBAM system aligns directly with the EU’s climate policy. As the bloc reduces free carbon allowances for local producers, CBAM increases the carbon cost for imported goods to match. This prevents emissions shifting outside the EU and pushes suppliers toward lower-emission production methods.
If you import covered goods, CBAM affects your procurement, compliance, and supplier relationships. You’ll need reliable carbon data from suppliers, systems to track product-level emissions, and a plan to manage certificate purchases once the financial obligations start.
How CBAM Certificate Costs Are Calculated
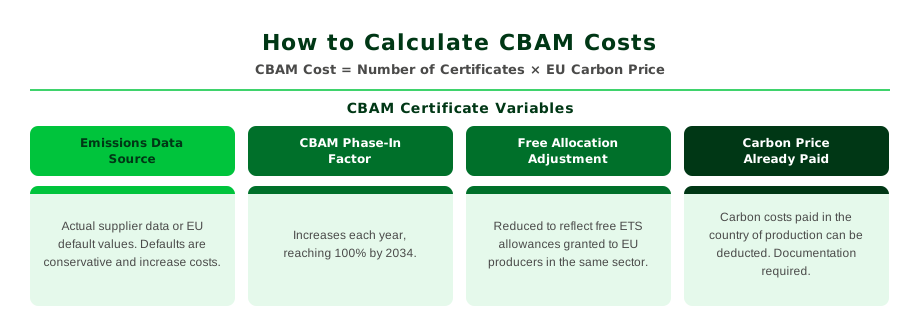
CBAM costs are calculated by multiplying the number of certificates you owe by the current EU carbon price. Several variables determine how many certificates you owe, and small differences in each can change your total exposure.
- Embedded emissions: Whether you use actual supplier data, an approved equivalent method or default values will materially affect your certificate count. Default values are intentionally conservative and typically result in higher costs than verified supplier data.
- CBAM phase-in factor: CBAM does not require certificates for 100% of embedded emissions from the start. The percentage increases each year, reaching full coverage by 2034. Your certificate obligation today is lower than it will be as the mechanism matures.
- Free allocation adjustment: Your obligation is reduced to reflect any free ETS allowances still granted to EU producers in the same sector.
- Carbon price paid in the country of production: If your supplier already paid a carbon price in their home country, you can deduct that amount, though documentation is required, and eligible programs are still being clarified.
Because EU ETS prices fluctuate weekly and import volumes shift throughout the year, treat CBAM cost projections as scenario-based estimates rather than fixed numbers. Build in regular updates as carbon prices change and supplier emissions data improves.
CBAM Scope: Who Is Affected?
CBAM applies to companies that import specific goods into the EU’s customs territory, across all EU member states. There are no exemptions based on the country of origin. However, if the exporting country has a carbon pricing system in place, you can account for that in your reporting and reduce your cost obligation.
You are in scope if you are the importer of record for CBAM-covered goods. That includes EU-based manufacturers, distributors, or traders sourcing from non-EU suppliers. CBAM applies to whoever clears the goods through EU customs, even if they are not an end user of a product.
Non-EU suppliers are not directly regulated under CBAM, but their data is essential. You’ll need information from those suppliers to calculate and report the emissions embedded in the goods they produce. Without accurate data, you may have to rely on default values, which can increase your certificate costs. This means procurement and sustainability teams need to engage with suppliers and collect product-level emissions data throughout the year.
Importers below 50 tonnes of CBAM-covered goods per year are fully exempt from all CBAM obligations, including reporting, authorization and certificate purchases. This threshold applies per product group and replaces the former €150 consignment value exemption. This exempts an estimated 182,000 importers, mostly SMEs and individuals, while still capturing over 99% of emissions.
CBAM Timeline: Transitional Phase and Full Implementation
CBAM rolled out in two phases. The first was a transitional period focused on reporting. The second introduced financial obligations. The transitional phase is complete. The definitive phase, which carries real financial consequences, is now in effect.
The Transitional Phase: 2023 to 2025
The CBAM transitional phase is complete. From October 2023 through the end of 2025, importers were required to report emissions but did not have to pay. This period gave importers time to build internal processes, engage suppliers and identify data gaps before financial obligations applied.
During this phase, importers submitted quarterly reports covering embedded direct emissions from imports, using actual emissions data from producers where possible. No certificate purchases or third-party verification were required. The last quarterly report covering Q4 2025 was due January 31, 2026.
The Definitive Phase: From 2026
The definitive phase is now in effect. Financial liability applies to all CBAM-covered imports made from January 1, 2026 onward. Importers above the 50-tonne threshold must hold Authorized CBAM Declarant status, granted by their national authority. The EU simplified the authorization process by removing the consultation requirement and introducing digital tools.
Third parties, like customs brokers or consultants, can be appointed to manage filings on your behalf. You remain responsible for compliance, but the administrative work can be delegated. This is particularly useful for companies managing high import volumes or complex supply chains across multiple product categories.
Here is what the definitive phase requires:
- Submit an annual CBAM declaration covering all imports from the previous year
- Surrender CBAM certificates equal to the total emissions reported
- Purchase certificates at a price based on the weekly EU ETS average
- Deduct carbon prices paid in the country of origin (documentation needed)
- Have emissions data verified by an independent third party
- Maintain certificate holdings covering at least 50% of required certificates on a quarterly basis
- Use the CBAM registry to manage declarations, certificates, and supporting documents
CBAM reporting covers direct emissions, including emissions from electricity used in production. Indirect emissions from heat, steam and cooling are excluded, which narrows the data you need to collect from suppliers and simplifies verification.
Submissions, certificate management and regulator communications all run through a single digital CBAM portal. Suppliers with verified emissions data can upload it directly to the registry, which you can then reference in your declarations.
You’ll need to budget for certificate purchases, gather verifiable emissions data at the product level, and make sure your suppliers can support those requirements. Delays, gaps, or incorrect data could increase costs or trigger penalties.
How CBAM Fits with Other Climate and ESG Regulations
CBAM doesn’t stand alone. It links directly to the EU’s carbon market and overlaps with other emissions and ESG regulations. If you manage compliance or sustainability reporting, you’ll need to understand how CBAM connects to these frameworks.
CBAM and the EU Emissions Trading System (EU ETS)
CBAM mirrors the EU ETS. While EU manufacturers pay for emissions through the ETS, CBAM applies the same carbon cost to certain imports. If you bring in steel, aluminum, or other CBAM-covered products, you’ll face similar charges through CBAM certificates.
The EU is phasing out free ETS allowances for EU producers in CBAM sectors between 2026 to 2034. As these disappear, CBAM will expand. This balances competition between local and foreign producers.
CBAM and ESG Reporting Requirements
CBAM requires you to report product-level emissions. This aligns with data you may already collect under CSRD, GHG Protocol, or national rules like California’s SB 253. If you track scope 3 emissions from purchased goods, you’re already doing part of the work.
Use the same methods and standards across your reports. GHG Protocol methods, lifecycle assessments, and verified supplier data can support both CBAM and ESG disclosures. If you run sustainability reporting, loop in your trade and compliance teams. CBAM data should feed into your emissions disclosures. Doing this early will help avoid mismatches in public reports.
Potential Future Developments
CBAM is the first mechanism of its kind, but others are watching. The UK, Canada, and Japan are considering similar carbon pricing for imports. Global suppliers may soon face carbon costs in multiple regions.
Trade policy is also changing. The EU designed CBAM to follow WTO rules, but some countries have raised objections. If you operate across borders, track how carbon tariffs evolve. What applies in the EU today could show up elsewhere tomorrow.
The EU may expand CBAM after 2030 to cover more products and emissions. Indirect emissions or downstream products could be next. If you want to prepare, map your carbon data now, not just for current imports, but across your supply chain.
Addressing CBAM Compliance Challenges
CBAM compliance goes beyond filing a few reports. You’ll need to manage emissions data from non-EU suppliers, align your reporting with EU methodologies, and build new internal processes. These requirements cut across procurement, sustainability, compliance, and finance teams.
Data Collection and Accuracy
According to the EcoVadis Carbon Action Report 2025, only 11% of companies actively collect primary emissions data from suppliers. That means the majority of CBAM-affected importers are starting from a significant data gap.
CBAM requires accurate, product-level emissions data for every shipment you import. That requires requesting and receiving emissions data directly from your non-EU suppliers. Many suppliers don’t track this data in a way that aligns with CBAM rules, or don’t track it at all. Some may only have facility-wide averages. Others may provide emissions figures based on incompatible methods or metrics.
If you can’t obtain usable data, you’ll need to rely on default values published by the Commission. These defaults are typically set higher than most real-world values, which means you’ll likely pay more in certificates than necessary. To reduce costs and risks, you need to identify which suppliers are in scope, collect relevant data and verify that it meets CBAM requirements.
Supplier Engagement and Collaboration
You can’t comply with CBAM without your suppliers’ cooperation. While CBAM doesn’t regulate non-EU producers directly, you need their input to calculate and report emissions. That means working with suppliers who may be unfamiliar with carbon reporting and lack systems to generate the data you need. Some may resist sharing sensitive production information. Others may not have the resources to follow EU methodologies.
You’ll need to educate them, provide clear guidance, and set expectations early, especially with key or high-volume suppliers. Larger companies may be able to roll out standardized engagement programs. Smaller ones may need to rely on platforms or external partners to manage outreach and follow-up.
Verification and Documentation
CBAM now requires emissions data to be verified by an independent third party, so you’ll need to plan for verification at the supplier level and track documentation for every declared shipment. You’ll also need to store audit trails, verification reports, and evidence of carbon prices paid outside the EU, if applicable.
This requires clear roles and workflows between your team and your suppliers. If you don’t build verification planning into your timeline, you risk missing deadlines or having incomplete submissions. You may also need to validate the credibility of third-party verifiers working across countries and production types. All of this adds time, cost, and operational pressure, especially in the first reporting cycles.
Timing and Reporting
CBAM adds new reporting tasks on top of your existing ESG or compliance workload. You now need to prepare an annual declaration, purchase and surrender certificates, and meet the September and October deadlines each year. CBAM certificates will be available in February 2027 for 2026 emissions.
These dates won’t always align with your internal reporting or audit cycles, which can lead to process conflicts or delays. You’ll also need systems in place to track emissions data throughout the year, not just at year-end. If you’re operating in multiple EU countries or managing multiple suppliers, the volume of submissions, and documents can grow quickly.
Regulatory Change Management
CBAM rules are still evolving. The Omnibus Simplification Package, introduced binding changes to thresholds, timelines, and verification requirements. Future updates are likely as the EU expands the scope, refines methodologies, or responds to feedback from importers.
You’ll need to monitor regulatory changes and update your internal processes and tools accordingly. If you operate across multiple jurisdictions, you’ll also need to reconcile CBAM requirements with other applicable carbon disclosure rules and frameworks.
Building a Scalable CBAM Compliance Program
CBAM isn’t a one-time filing task. It’s an ongoing compliance function that affects procurement, sustainability, finance and trade. To manage it effectively, companies need systems that can support supplier engagement, carbon data collection, emissions calculations, and reporting workflows across multiple geographies and product lines.
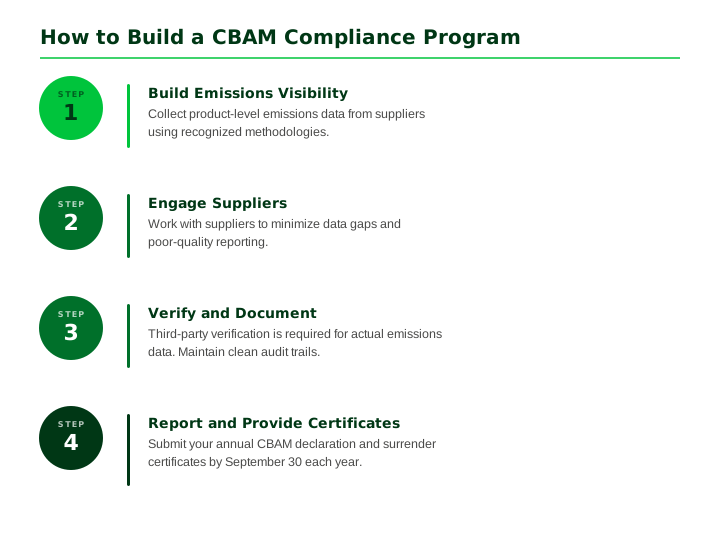
Build visibility into your supply chain emissions. That means working with suppliers to access product-level emissions data, ideally based on recognized methodologies. Many organizations are moving away from ad hoc spreadsheets and manual outreach toward structured assessments and centralized data platforms. These tools make it easier to collect and standardize emissions data from hundreds of suppliers, track who’s reporting, and flag data gaps before reporting deadlines. Data gathered and stored in a consistent format also makes verification more manageable, reducing the risk of errors or missed obligations.
Engage suppliers proactively. Companies that approach CBAM reactively by requesting emissions data at the last minute are likely to run into delays, resistance, or poor-quality reporting. Instead, building ongoing engagement programs that support suppliers in understanding and improving their carbon performance is more effective. Some companies are integrating carbon maturity assessments into onboarding or quarterly reviews to track progress over time and help suppliers prepare for future verification requirements.
Integrate CBAM data into your broader ESG reporting. The same data that supports CBAM filings can inform sustainability disclosures, track scope 3 emissions, and strengthen investor reporting. Aligning emissions reporting across functions reduces duplication and supports long-term climate targets.
Use platforms and tools to scale. For organizations managing large supplier bases or complex import portfolios, manual processes won’t hold up. EcoVadis supports companies with tools to collect and assess supplier carbon data, engage value chain partners, and strengthen emissions transparency across procurement networks.
To find out how EcoVadis can support your CBAM compliance efforts, talk to our team.
FAQs
Q: Who is required to comply with CBAM?
A: Any company that imports CBAM-covered goods into the EU’s customs territory is required to comply. This includes:
- EU-based manufacturers importing directly from non-EU suppliers
- Distributors and traders sourcing CBAM-covered goods from outside the EU
- Any importer of record who clears CBAM-covered goods through EU customs, regardless of whether they are the end user
Importers with total annual net imports below 50 tonnes of CBAM-covered goods are exempt from all obligations.
Q: How do I know if I’m below the 50-tonne CBAM exemption threshold?
A: The threshold applies per product group. If your total annual net imports of a CBAM-covered product category fall below 50 tonnes, you are exempt from all obligations for that category. Monitor your volumes throughout the year. If you cross the threshold for any product group, full compliance obligations apply for that category for the entire year.
Q: What emissions data do I need from my suppliers for CBAM?
A: You need product-level emissions data covering the direct greenhouse gas emissions produced during manufacturing, including emissions from electricity used in production. Indirect emissions from heat, steam and cooling are excluded.
Where possible, this data should be based on actual emissions verified by an independent third party. If your supplier cannot provide actual data, you can use default values published by the European Commission, though these are set conservatively and will typically result in higher certificate costs.
Q: What qualifies as an authorized CBAM declarant and how do I register?
A: An authorized CBAM declarant is an importer registered to submit CBAM declarations and purchase certificates. To qualify, you must be established in the EU and approved by your national competent authority. The EU has simplified the registration process by removing the previously required consultation step. Applications are submitted through the CBAM registry. Importers above the 50-tonne threshold must hold authorized declarant status before importing CBAM-covered goods.
Q: What documentation do I need to support a CBAM declaration?
A: All documentation is managed through the CBAM registry. You will need:
- Product-level emissions data for each imported good
- Third-party verification reports where actual emissions data is used
- Evidence of any carbon prices paid in the country of production
- Records of import volumes throughout the year
Maintaining clean audit trails from data collection through to declaration submission will reduce the risk of errors and support regulatory reviews.